

NONPROFIT FILING REQUIREMENTS
Form 990 Filing for PTAs &
Parent Teacher Groups
Every PTA, PTSA, PTO, and parent group with tax-exempt status has its own annual Form 990 to file, even when it's covered under a state PTA's group exemption. Tax990 makes it easy to track, prepare, and e-file each unit's return from a
single account.

WHY YOU NEED TO FILE
Do PTAs have to file Form 990?
Yes. A PTA exempt under 501(c)(3) must file a Form 990-series return every year, whether it holds its own IRS determination letter or is covered as a subordinate unit under its state PTA's group exemption. Being exempt from income tax doesn't remove the annual reporting requirement, and missing three years in a row triggers automatic revocation.
WHO NEEDS TO FILE
PTAs & Parent Groups That Must File 990
Tax-exempt status belongs to whichever organization the IRS recognizes, and every unit with its own EIN answers to the IRS on its own.
The school's EIN and the state PTA's group ruling don't file for you.
Local PTA & PTSA units
Each unit files its own 990-series return under its own EIN, even as a subordinate under the state PTA's group exemption. A PTA should never use the school's EIN.
Council & district PTAs
Councils are separate units with their own EIN. They file their own return, apart from the local units they support.
PTOs & independent parent groups
Groups outside the National PTA aren't covered by any PTA group exemption. They need their own 501(c)(3) recognition to be a 990 filer. Without it, they're taxable and generally file Form 1120.
Special education PTAs (SEPTAs)
District-wide special education PTAs are chartered units in their own right and file separately from the school-level PTAs they work alongside.
Booster clubs & parent committees
Band, athletic, or arts boosters set up apart from the PTA, with their own EIN, have their own filing requirement. A committee running under the PTA's EIN is reported on the PTA's return.
School & education foundations
A separately formed foundation or scholarship fund with its own 501(c)(3) status files its own Form 990, even if the PTA helped
create it.
FILING REQUIREMENTS
Which 990 Form does your PTA need?
The form depends on your PTA's size, not on its school or its National PTA affiliation. Two numbers
decide it: gross receipts and total assets.


DUE DATE
When to file 990 for
your PTA?
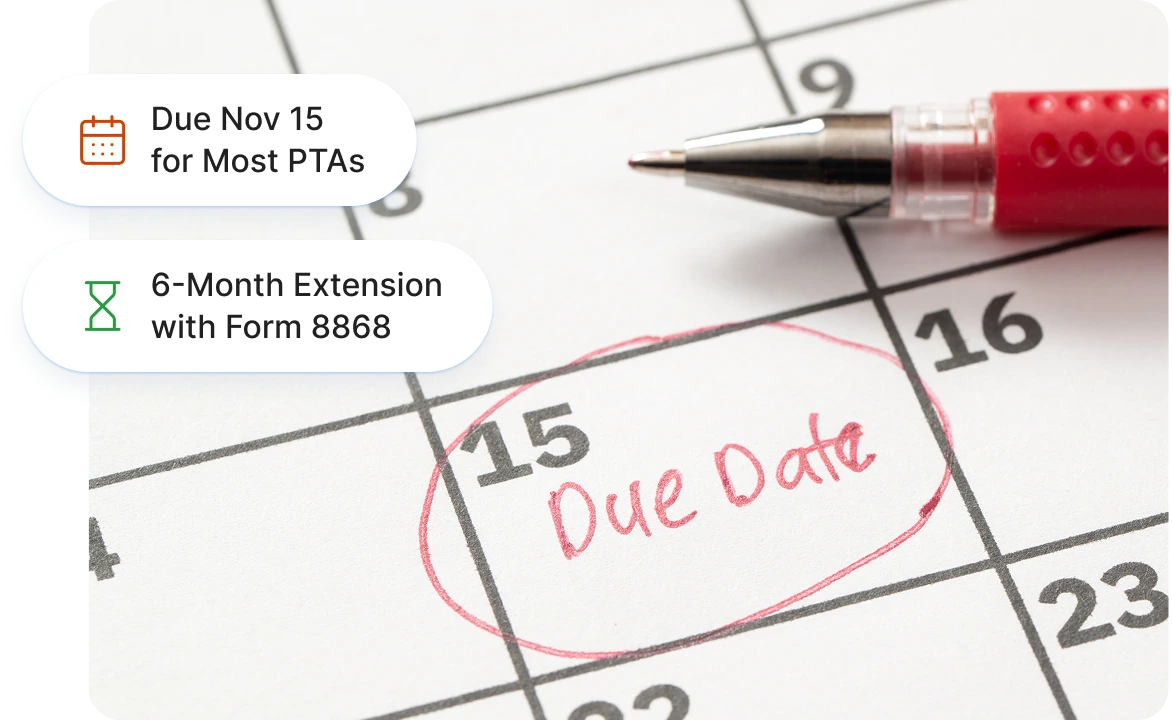
Form 990 is due on the 15th day of the 5th month after the end of the PTA's tax year. Most PTAs follow the school year (July 1 – June 30), so their return is due November 15. PTAs on a calendar tax year file by May 15. If the date lands on a weekend or holiday, the return is due the next business day.
Need more time? Form 8868 gives an automatic 6-month extension when it's filed by the original due date. Form 990-N can't be extended.
WHY TAX990
Meet your PTA's 990 filing requirements
with
Tax990
One platform built for volunteer treasurers, from a single school unit to an entire council,
without the guesswork.
Guided filing
A plain-language, step-by-step interview. No tax background needed.
Built-in error checks
An internal audit catches mistakes before the return
goes to the IRS.
Board review, built in
Share the return with your president or board
to review and approve before filing.
Copy prior-year data
Carry last year's details forward, so a new treasurer never starts from scratch.
Includes schedules
Required schedules, such as A and B, are generated for
you at no extra cost.
Multi-unit filing
Councils and state PTAs can manage many local units'
returns from one account
Learn more.
PROTECTION & COMMITMENT
Support That Lasts Beyond Filing
The Tax990 Commitment
From first click to filing, and beyond,
we've got your PTA's back
You can trust Tax990 to do everything in our power to ensure your 990-EZ forms are filed correctly.
-
 Complimentary extension requests if you need
more time -
 No-cost amendments in case anything needs to
be updated -
 Free retransmission if the IRS rejects
your return -
 Money-back guarantee so you can file
with confidence

$1M Tax Protection™ for 990 Forms
Tax990 partners with Protection Plus

Up to $1M Tax Protection™
Up to $1M in protection on your filed 990.

Expert IRS Notice Assistance
Expert help responding to IRS notices.
FAQs
Frequently Asked Questions
No. A PTA is tax-exempt only after the IRS recognizes it, either through its own 501(c)(3) determination letter or as a subordinate unit listed under its state PTA's group exemption. Being nonprofit and connected to a school doesn't create exemption on its own.
Yes. A group exemption covers your exempt status, not your annual return. Each local unit files its own 990-series return under its own EIN, and your state PTA may ask for a copy to keep you in good standing.
The IRS filing rules are the same: the same forms, thresholds, and deadlines apply. The difference is exemption. A PTO isn't affiliated with the National PTA, so it can't rely on a PTA group exemption and must get its own 501(c)(3) recognition.
A PTA gets its own EIN, then files Form 1023 or Form 1023-EZ with the IRS. The EZ version is open to organizations that project annual gross receipts of $50,000 or less and hold total assets of $250,000 or less. Keep the IRS determination letter as a permanent record.
No. The PTA is a separate organization from the school and the school district. It needs its own EIN for its bank account, its exemption, and its Form 990.
Late Form 990 and 990-EZ returns can draw IRS penalties of $25 per day, up to the lesser of $13,000 or 5% of the PTA's gross receipts (2026 amounts). Larger organizations face higher penalties. Missing any required return for three consecutive years automatically revokes tax-exempt status.
Yes, through reinstatement. That generally means filing a new Form 1023 or 1023-EZ, along with any required past-due returns. Contact your state PTA as well, since your unit may need to be restored under the group exemption.
Usually not. Activities run almost entirely by unpaid volunteers, and sales of donated items, are generally excluded. A PTA that earns $1,000 or more in gross income from a regularly carried-on business unrelated to its purpose must file Form 990-T in addition to its regular return.
Yes. Form 8868 requests an automatic 6-month extension for Form 990, 990-EZ, or 990-T. It has to be filed on or before the original due date. Form 990-N has no extension.
Yes. Each unit's return stays separate under its own EIN, but a council or treasurer can manage them all from a single Tax990 account.
The PTA files a final 990-series return marked as final, or checks the termination box on Form 990-N. Remaining assets must go to another exempt organization as its bylaws direct, never to individual members.
ALL YOUR FILING REQUIREMENTS COVERED
Keep Your PTA in Good Standing
One account for your PTA and every council, booster group, or foundation connected to it.
Guided, IRS-authorized, and backed by $1M in
audit protection.
PTAs must file every year to keep their exempt status
and their standing with the state PTA.